asset tokenization trends
Asset tokenization trends point toward a practical change in private capital markets: representing investments digitally can simplify ownership records, support smaller allocations, and make transfers easier. But tokenization cannot guarantee liquidity. A private investment still needs eligible buyers, reliable valuations, and workable exit terms.
That distinction matters when money could remain committed for years. Easier access sounds appealing. Getting your money back is a separate question.
The opportunity is real, but so are the limits.
What Tokenization Actually Changes
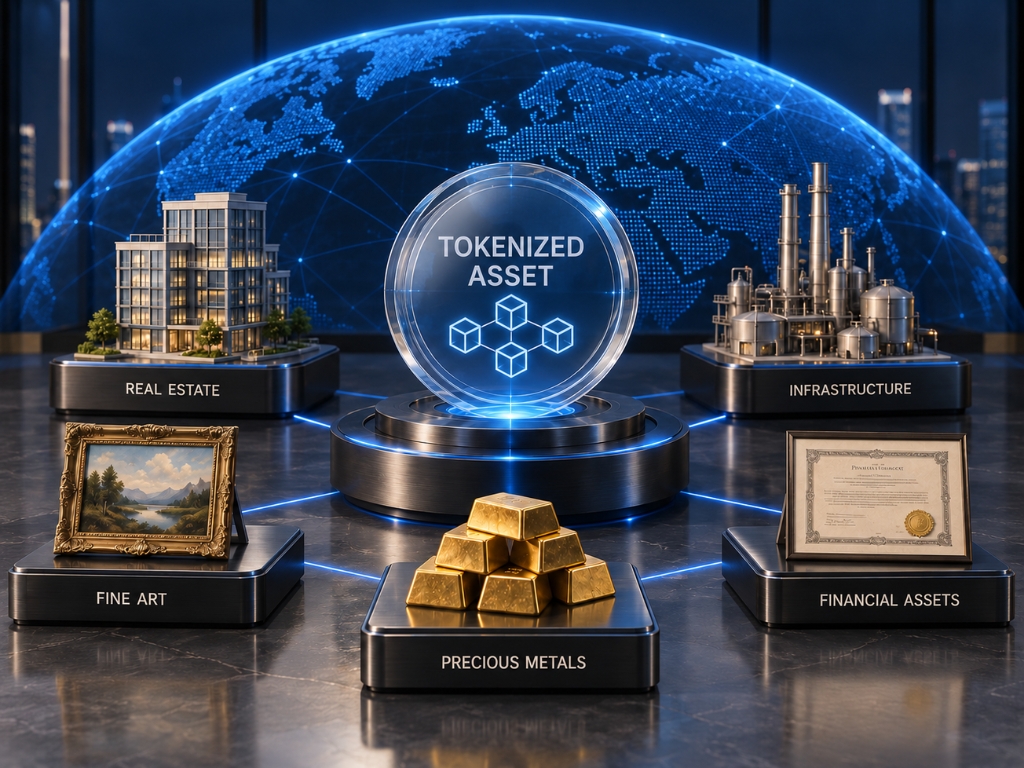
Real-world asset tokenization means representing rights connected to an asset through digital tokens. Those rights might relate to a bond, a fund holding, or shares in a company that owns property. A distributed ledger is a shared digital record. It can help participants maintain consistent transaction information, reducing the need to reconcile separate records.
A token doesn’t automatically give its holder direct ownership of the underlying building or business. The legal documents determine whether it represents shares, debt, fund units, or another claim. Always start there. The technology describes how an investment is recorded; the documentation explains what you own.
Asset Tokenization Trends Beyond the Hype
Institutional interest increasingly concerns the mechanics of financial market infrastructure: issuing securities, recording ownership, transferring assets, and settling payments.
Settlement means completing a transaction by delivering the asset and payment. Programmable systems can coordinate those steps and automate certain instructions. They may also reduce repetitive administration. bis.org
Faster settlement is a potential benefit, rather than a universal feature. Payment arrangements, legal requirements, and connections between systems still influence how quickly transactions finish. For businesses assessing digital ledger capital markets solutions, the useful question is specific: which existing process becomes cheaper, faster, or more reliable?
Fractional Ownership Helps Entry, Not Necessarily Exit
Private equity fractional ownership can allow investors to purchase smaller interests where the product structure permits it. That may broaden participation without requiring each investor to commit a large sum. Still, smaller tickets don’t remove investment restrictions. Eligibility rules, fund terms, and local securities laws continue to apply.
Consider a hypothetical token representing an interest in commercial property. Dividing the investment into smaller units doesn’t make the property easier to sell, improve rental income, or create buyers for those units. Asset tokenization trends can improve transfer mechanisms. Actual liquidity in private assets depends on demand, pricing, and permitted transactions. Confusing those two things can leave investors expecting an exit that never arrives.
Bonds Offer a Different Use Case
The tokenized bond market shows how digital representation can support issuance, servicing, and settlement. Government bond tokenization could improve efficiency, although regulatory and infrastructure challenges remain. Private credit and property involve different risks. Their valuations may be less frequent, and their underlying assets may take longer to sell.
A token backed by a fund holding government bonds is also different from a government bond issued directly on a digital platform. Compare the legal structure and redemption terms before comparing yields. Digital asset investment remains an investment. Borrowers can default, asset values can fall, and fees can reduce returns.
 real world asset tokenization
What the UK Developments Show
For anyone following tokenization UK capital markets developments, the Digital Securities Sandbox provides a concrete example. Operated by the Bank of England and FCA, it allows firms to explore developing technologies for securities trading and settlement within a regulated framework.
That supports experimentation with real market processes. It doesn’t establish that every tokenized product is suitable for every investor. Participation in a regulatory sandbox should never be read as a guarantee of returns or easy resale. Asset tokenization trends deserve attention without treating adoption as proof of investment quality.
Smart Moves Before Committing Capital
Whether raising money or investing, check the essentials:
- Establish the exact legal rights attached to each token.
- Review investor eligibility, transfer restrictions, and redemption terms.
- Check trading activity rather than relying on promised liquidity.
- Understand custody, cybersecurity, and platform failure arrangements.
- Compare total costs with a conventional investment structure.
Issuers should pilot a clearly defined process before replacing an entire fundraising system. Investors should keep money needed soon outside assets with uncertain exits. Liquidity mismatches can become dangerous when tokens appear easier to redeem than the underlying assets actually are. Executive Summary
Keep the Investment Case First
Asset tokenization trends could make private capital markets more efficient and accessible. The strongest opportunities solve identifiable administrative or settlement problems while preserving clear legal rights. Before committing money, assess the asset, its cash flows, its costs, and its exit arrangements. Better technology can improve the investment process. The underlying investment still has to justify the risk.