central bank decisions
The September central bank decisions have changed the interest-rate conversation going into the final quarter of 2026. Instead of the broad easing cycle many households had hoped for, the Federal Reserve and European Central Bank both raised rates by 25 basis points, while the Bank of England held its benchmark rate steady at 3.75%.
That matters for mortgages, savings accounts, credit cards, and investment portfolios. It is easy to feel unsure when three major central banks move differently within days of one another. The important part is understanding what those moves actually change for household finances.
Central Bank Decisions Are Turning More Cautious Again
The September meetings show a renewed focus on inflation.
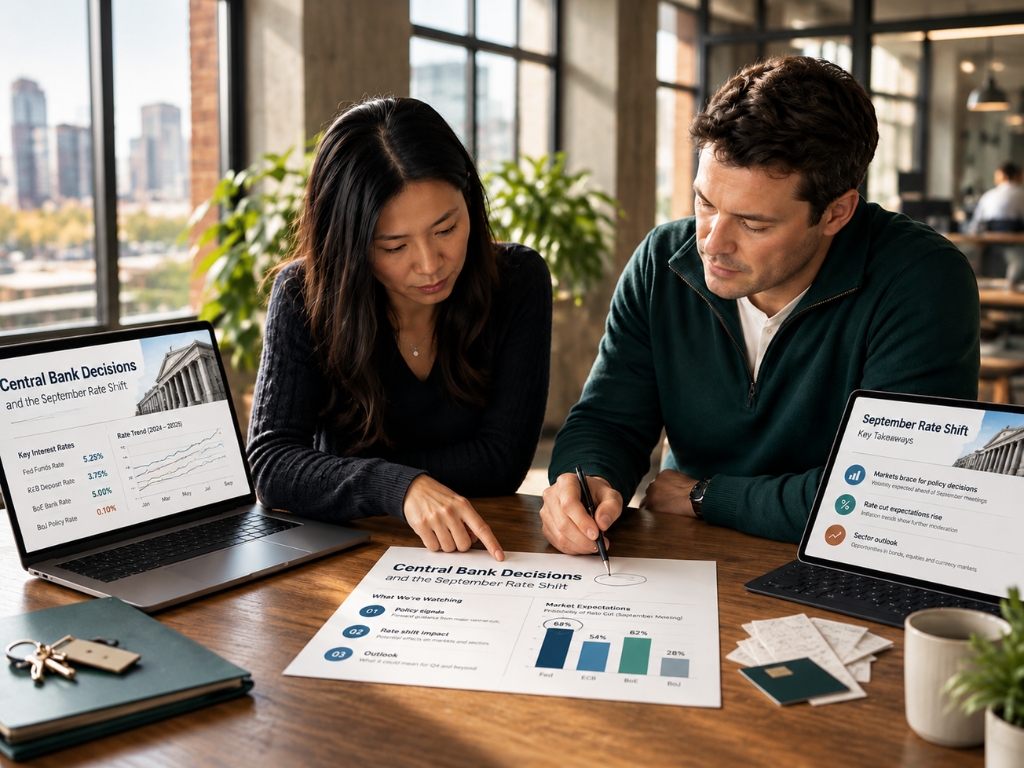
The Fed raised its federal funds target range to 3.75%–4.00%, saying inflation remained elevated even as economic activity continued to expand at a solid pace. The ECB also lifted its three key rates by 0.25 percentage points, taking its deposit facility rate to 2.50%. Its latest projections put euro-area inflation at 3.0% for 2026 and 2.5% for 2027, largely reflecting continued energy-related pressure.
The BoE chose not to hike, but the vote was hardly relaxed. Six members supported keeping the bank rate at 3.75%, while three preferred an increase to 4%. UK CPI inflation reached 3.1% in August, and the Bank said risks to the inflation outlook had shifted further upward. So the real Fed vs BoE policy divergence is about timing, not a simple split between tightening and easing.
Why Inflation Is Driving the September Shift
Central banks constantly balance inflation vs. economic growth. Inflation simply means prices are rising across the economy. Higher policy rates can slow that process by making borrowing more expensive, which reduces spending and investment.
The problem is that expensive energy has returned as a major pressure point.
Both the ECB and BoE explicitly highlighted higher energy costs linked to the continuing Middle East conflict. That makes monetary policy decisions harder because raising rates cannot directly produce more oil or gas. It can only prevent higher costs from spreading more broadly into wages and prices. That tension will dominate the interest rate outlook Q4.
How Central Bank Decisions Affect Your Mortgage
The mortgage rate impact depends heavily on the type of loan.
Variable-rate and adjustable-rate borrowers tend to feel policy changes more directly because their borrowing costs can move with short-term benchmark rates. Fixed mortgages are different. Longer-term fixed mortgage rates depend heavily on government bond yields and expectations about future inflation, not just the central bank’s headline rate.
That distinction matters now. The Bank of England noted that quoted two-year fixed mortgage rates were around 95 basis points higher than before the latest geopolitical conflict pushed financial conditions tighter. Someone approaching a mortgage renewal should therefore compare current offers rather than assuming rates will soon fall simply because economic growth softens.
Savings Yield Changes Could Stay Favorable for Longer
For savers, September has produced a different message from the one in the original rate-cut narrative. Higher or steady central bank rates can keep savings yields relatively attractive. Banks do not pass every rate increase directly to customers, so high-yield savings accounts, money-market products, and term deposits still need to be compared carefully. But there is less reason to expect an immediate collapse in cash yields when major central banks are either hiking or holding rates at restrictive levels.
A fixed-term deposit may make sense for money that will not be needed soon. But locking every spare dollar or pound into a long-term account can create another problem: losing access to emergency cash. Liquidity still matters.
What September Market Volatility Means for Investors
Market volatility in September has been driven by changing expectations for rates, inflation, oil prices, and government bond yields. Higher rates can pressure highly valued growth companies because future profits become less valuable when investors can earn more from safer assets. At the same time, banks and some financial companies may benefit from wider interest margins.
There is no automatic “rate hike portfolio.”
Markets often price anticipated policy moves before central banks announce them, which means reacting after headlines can leave investors chasing moves that have already happened. A diversified allocation remains more useful than trying to predict which sector will react best to every meeting.
 central bank rate decisions September
Quick Smart Moves for Q4
A few practical checks can make the latest central bank decisions easier to manage:
- Review variable-rate loans and know when the next reset occurs.
- Compare mortgage refinancing costs before switching lenders.
- Check savings APYs rather than assuming your existing bank remains competitive.
- Keep emergency money accessible before locking cash into term deposits.
- Pay down expensive credit-card balances where possible.
- Avoid making major portfolio shifts purely because of one rate announcement.
- Watch inflation and bond yields alongside central-bank headlines.
These steps are simple, but they directly address the areas most exposed to changing rates.
What Comes Next
The biggest mistake now would be assuming that September guarantees a straight path toward either higher or lower rates.
The ECB has said future decisions will remain data-dependent. The Fed continues to focus on returning inflation toward 2%, while the BoE has justify the door open to action if persistent energy costs spread further into domestic prices. That means the interest rate outlook for Q4 remains sensitive to inflation, energy markets, wages, and economic growth.
Conclusion
September’s central bank decisions matter because they show that inflation risk is back at the center of monetary policy. The Fed and ECB raised rates, while the BoE held steady but signaled greater concern about future price pressures. For households, that means mortgage relief may arrive more slowly than expected, while savings yields could remain relatively attractive. The practical response is not to predict the next central-bank move. It is to know which debts carry variable rates, keep savings competitive and accessible, and avoid making investment decisions based on a single policy meeting. That approach gives personal finances more room to absorb whatever Q4 brings.